Connect with Us


How Early Detection Improves Treatment Outcomes for Serious Illnesses
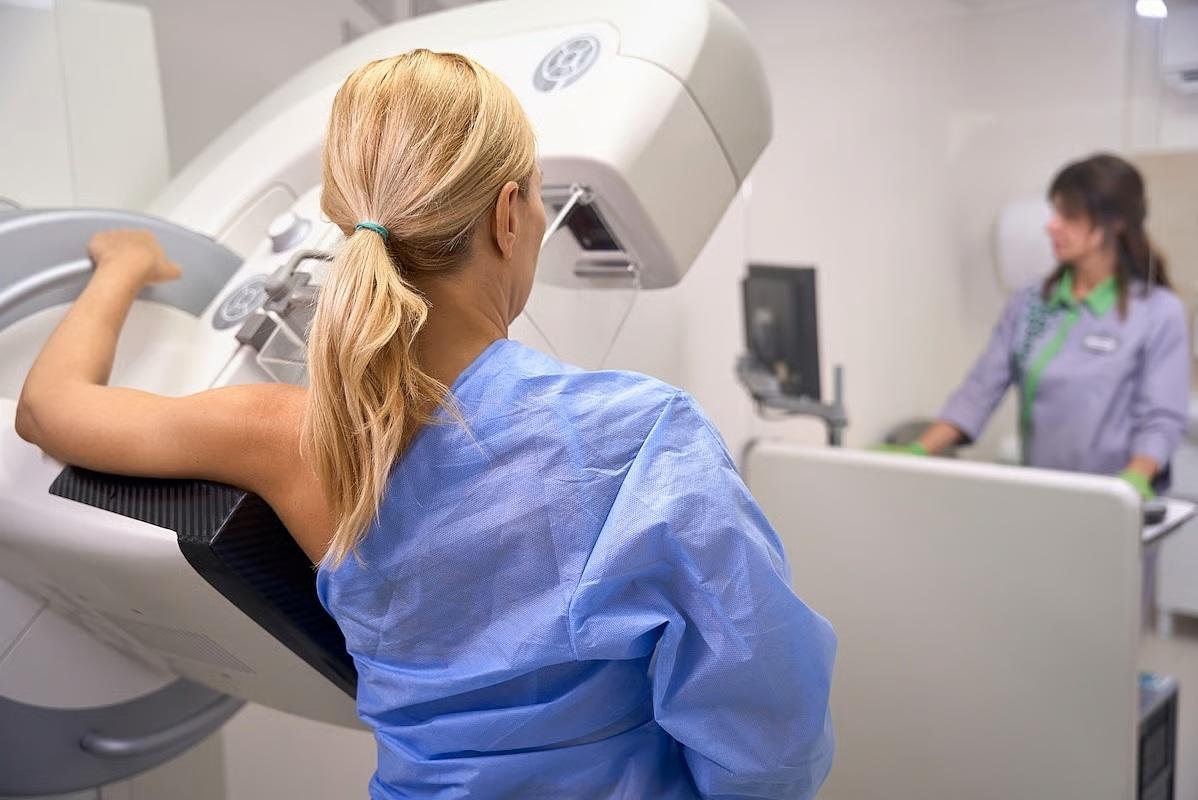
For decades, the American healthcare system has operated on a fundamentally reactive model, waiting for patients to fall visibly ill before deploying expensive, intensive interventions. However, the medical and economic realities of 2026 are forcing a massive shift toward proactive health management. When examining early detection treatment outcomes, the clinical consensus is clear: identifying a severe illness before symptoms manifest is the single most effective way to improve a patient’s long-term survivability.
Beyond the obvious clinical benefits, early detection has become a crucial focal point in the broader conversation about healthcare affordability. Treating advanced-stage chronic conditions or late-stage cancers places an unsustainable financial burden on both the patient and the insurance risk pool. Understanding how preventative screenings alter the trajectory of a diagnosis—and knowing how insurance networks cover these critical tests—is essential for any consumer looking to protect their health and their household budget.
The Clinical And Financial Value Of Preventative Care
When major diseases such as cardiovascular disease, diabetes, or cancer are caught in their earliest stages, the treatment protocols are vastly different than when they are diagnosed late. Early intervention typically requires less aggressive therapies, shorter hospital stays, and lower dosages of specialty medications. This translates directly into significantly higher survival rates and a much faster return to a normal quality of life for the patient.
From a financial perspective, early detection is arguably the most powerful cost-containment tool available in modern medicine. The resources required to manage a localized, early-stage tumor are a fraction of the millions of dollars routinely billed for advanced chemotherapy, complex surgeries, and extended intensive care admissions. By shifting the focus to routine checkups and baseline testing, the healthcare system attempts to circumvent the catastrophic medical claims that drive up annual insurance premiums for everyone.
How Federal Mandates Guarantee Free Screening Access
To encourage widespread participation in preventative healthcare, the Affordable Care Act mandates that most private health insurance plans cover a specific list of evidence-based screenings at no out-of-pocket cost to the patient. This means that if a screening is explicitly recommended by the U.S. Preventive Services Task Force with an “A” or “B” rating, insurance companies cannot charge a copayment, coinsurance, or apply the cost to the patient’s annual deductible.
This federal protection ensures that financial anxiety does not deter patients from scheduling critical baseline exams like mammograms, colonoscopies, and routine blood pressure checks. Even if a patient has not yet met their high deductible for the year, these specific, age-appropriate preventative services must remain entirely free of charge when performed by an in-network provider. However, the strict definitions governing these free services often lead to unexpected medical bills if consumers do not fully understand the coding rules.
Navigating The Hidden Costs Of Diagnostic Follow-Ups
The line between a “preventative” screening and a “diagnostic” procedure is one of the most confusing aspects of medical billing. If a patient goes in for a routine, preventative colonoscopy and the physician finds and removes a suspicious polyp, the insurance coding frequently changes from a preventative service to a diagnostic intervention. Once that diagnostic code is applied, the patient may suddenly be responsible for standard cost-sharing fees, including unexpected facility charges.
Furthermore, if a patient schedules a screening specifically because they are already experiencing symptoms, the visit is legally classified as diagnostic from the very beginning. Patients must be highly proactive when communicating with their doctors and billing departments to ensure they understand exactly how their appointments will be coded. Knowing these nuances is a critical part of effectively using health insurance coverage in 2026 without falling victim to surprise medical debt.
The Rise Of AI And Advanced Genomic Screenings
As we move deeper into 2026, the technology driving early detection is advancing at a staggering pace. Medical providers are increasingly utilizing artificial intelligence algorithms to review routine imaging, catching microscopic abnormalities in lung and breast tissue that human eyes might miss. Simultaneously, the market is seeing a surge in “liquid biopsies”—simple blood tests capable of detecting fragments of cancer DNA long before a traditional tumor physically forms.
While these innovations promise to revolutionize early detection, they are currently at the center of intense coverage battles between hospitals and insurance carriers. Because many of these advanced genomic tests are new, insurers frequently categorize them as experimental and refuse to cover their high out-of-pocket costs. Until these cutting-edge diagnostics are universally adopted into federal preventative guidelines, patients will likely face an uphill battle securing insurance authorizations for the most advanced screening tools available.
What This Means For Your Long-Term Health Strategy
Ultimately, achieving the best possible treatment outcomes requires the patient to act as the chief executive of their own healthcare journey. Waiting for a doctor to suggest a screening is no longer a viable strategy. Patients must educate themselves on their specific family medical history, understand the recommended screening ages for their demographic, and aggressively advocate for those tests during their annual wellness visits.
Health insurance is designed to protect against catastrophic loss, but its greatest value lies in its ability to fund preventative care. By taking full advantage of federally mandated free screenings, understanding the boundaries of diagnostic billing, and staying informed about emerging detection technologies, consumers can dramatically shift the odds in their favor. Early detection is the ultimate convergence of good medicine and smart financial planning.
Early Detection Economics At A Glance
| Market Factor | How It Functions | Impact On Patients |
| Clinical Intervention | Catches diseases before they spread or cause severe symptoms | Results in less aggressive treatments and higher survival rates |
| Federal Mandates | Requires insurers to fully cover specific preventative screenings | Removes upfront cost barriers for routine baseline exams |
| Diagnostic Billing | Shifts billing codes when abnormalities are found or symptoms exist | Can trigger unexpected deductibles and copayments |
| Advanced Screenings | Utilizes AI and DNA blood tests to spot early disease markers | Often requires exhausting insurance appeals due to high costs |
