Connect with Us


Why Healthcare Costs Keep Rising in the U.S. and What Patients Can Do

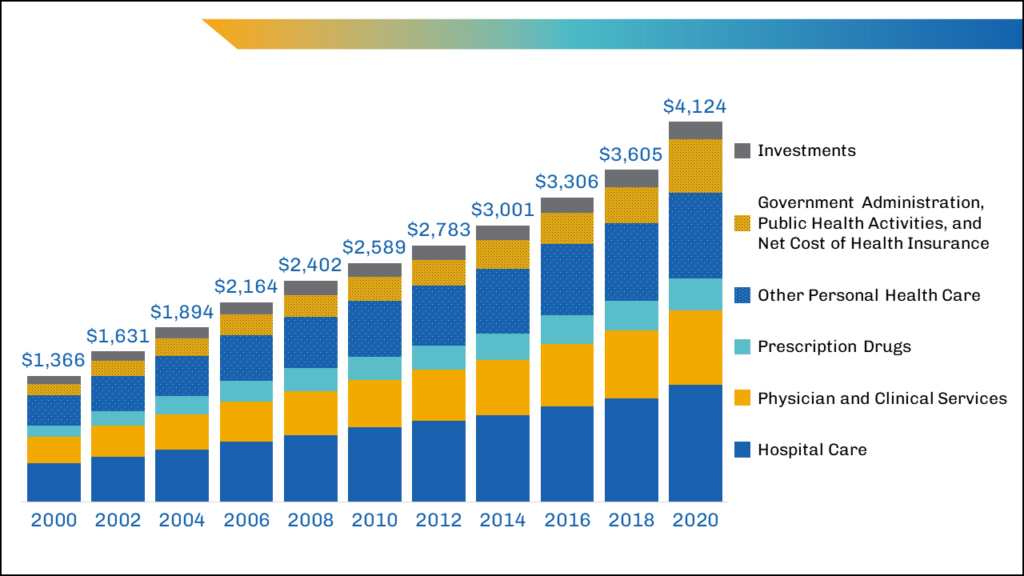
For the average American consumer, paying for medical care feels like an increasingly impossible financial hurdle. Moving through 2026, industry experts and actuaries anticipate that national healthcare costs will surge by eight to ten percent, significantly outpacing standard economic inflation. This relentless upward trajectory is not merely the result of a single broken policy, but rather a complex convergence of pharmaceutical breakthroughs, shifting demographics, and aggressive corporate consolidation.
Understanding why these expenses continue to climb is essential for anyone trying to navigate their annual enrollment period or decipher a frustrating hospital bill. While the macroeconomic forces driving the American medical system often feel entirely out of the patient’s control, identifying where the money is actually flowing empowers consumers to make strategic, defensive decisions about their personal health insurance coverage.
The Impact Of Hospital Consolidation On Pricing
One of the most significant yet least visible drivers of medical inflation is the aggressive consolidation of local healthcare markets. Over the last decade, massive regional health systems have systematically acquired independent physician practices, local clinics, and competing hospitals. This aggressive merging effectively creates regional monopolies, eliminating the natural market competition that typically keeps consumer prices in check.
When a single hospital system controls the vast majority of specialty care and emergency rooms in a specific county, they gain immense negotiating leverage. They use this dominance to demand significantly higher reimbursement rates from commercial insurance carriers. As we previously outlined in our analysis of the business of healthcare, insurance companies rarely absorb these rate hikes entirely. Instead, they pass the financial burden directly onto the consumer in the form of higher monthly premiums and steeper annual deductibles.
The Exploding Cost Of Specialty Drugs And GLP-1s
Pharmaceutical innovation is another primary catalyst for rising healthcare costs. The drug development pipeline has shifted dramatically away from low-cost, mass-market pills and toward highly complex specialty medications. Treatments like customized cell and gene therapies offer miraculous, life-saving potential for rare diseases and aggressive cancers, but they frequently launch with multi-million-dollar price tags that strain the entire health insurance risk pool.
Adding intense pressure to this dynamic is the unprecedented surge in demand for GLP-1 agonist medications. Originally developed for diabetes management, these high-cost injectables are now widely utilized for weight loss. With millions of Americans suddenly relying on medications that cost upwards of $1,000 per month indefinitely, employers and health plans are struggling to absorb the massive financial shock. This pharmaceutical spending boom forces insurers to constantly adjust their formularies and shift more prescription costs to the patient’s out-of-pocket maximum.
The Financial Burden Of An Aging Population
Demographics are fundamentally altering the economics of American medicine. The U.S. population is rapidly aging, with millions of individuals aging into their senior years and requiring exponentially more medical intervention. Older adults naturally utilize a disproportionate share of healthcare resources, frequently managing multiple, compounding chronic conditions such as heart disease, diabetes, and osteoarthritis simultaneously.
This demographic reality creates a volume problem for the healthcare system. Even if the unit price of a single doctor’s visit remained flat, the sheer frequency of required visits, diagnostic tests, and long-term care admissions for an aging population drives the total national healthcare expenditure upward. To support this massive utilization, healthcare facilities must expand their infrastructure and compete for a limited pool of specialized medical labor, driving up operational costs that eventually trickle down to the individual patient.
How Changing Subsidies Increase Your Out-Of-Pocket Exposure
Federal health policy acts as the final variable in the affordability equation. Throughout the early 2020s, enhanced federal subsidies artificially suppressed the cost of health insurance premiums for millions of middle-income Americans purchasing plans on the public marketplace. However, the expiration of these temporary protections in 2026 has abruptly reinstated strict income limits, causing monthly insurance bills to spike dramatically for households hovering just above the federal poverty line.
As government funding retreats, patients are forced to shoulder a much heavier percentage of the actual, unsubsidized cost of their care. Independent data monitoring from the Peterson-KFF Health System Tracker consistently shows that when policy shifts expose consumers to the raw cost of the medical market, patients frequently delay critical preventative care to save money. Unfortunately, delaying routine care inevitably leads to severe, advanced-stage illnesses that cost substantially more to treat in the long run.
What Patients Can Do To Protect Their Finances
While individual patients cannot stop hospital consolidation or single-handedly rewrite federal subsidy laws, they can adopt defensive financial strategies. The most crucial step is to abandon passive enrollment. During open enrollment, consumers must meticulously compare their plan’s maximum out-of-pocket limits against their anticipated medical needs, rather than simply selecting the policy with the lowest monthly premium.
Furthermore, patients must aggressively scrutinize their medical bills for unbundling errors or unexpected facility fees, which are common tactics used by large hospital systems to maximize revenue. Embracing preventative screenings, utilizing independent ambulatory surgical centers instead of hospital-owned outpatient facilities, and leveraging tax-advantaged Health Savings Accounts (HSAs) are all highly effective methods for insulating a household budget against the relentless surge of modern medical inflation.
Healthcare Cost Drivers At A Glance
| Economic Factor | How It Functions | Direct Impact On Patients |
| Hospital Consolidation | Health systems buy out local competition to gain market monopoly | Drives up regional prices and forces higher commercial insurance premiums |
| Specialty Pharmaceuticals | Massive spending on GLP-1 weight loss drugs and gene therapies | Triggers strict prior authorizations and higher prescription copayments |
| Shifting Demographics | An aging population requires significantly higher volumes of medical care | Increases systemic labor and facility costs that are passed to the consumer |
| Subsidy Expirations | The government rolls back enhanced premium tax credits in 2026 | Exposes middle-income earners to the full, undiscounted cost of health coverage |
